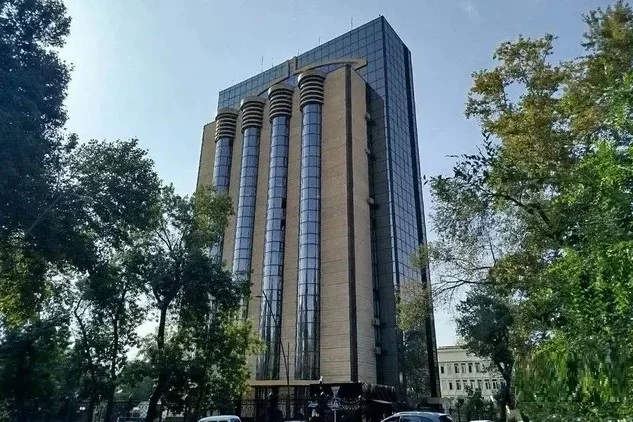
Uzbekistan’s central bank has issued the country’s first licence for Islamic banking operations. Open Bank received the licence. The regulator’s board approved the decision on Oct. 23.The licence permits Open Bank to conduct Islamic financial operations allowed under Uzbekistan’s banking law. These include profit-sharing financing, agency arrangements, instalment sales with a pre-agreed markup, advance payments for goods, joint project financing and Islamic leasing with a buyout option.
Islamic finance follows Shari’ah principles and prohibits interest-based lending. Banks use contracts such as mudaraba, which means profit-sharing, and wakala, which means agency. Murabaha covers sales with a profit. Salam covers advance payment. Musharaka covers partnership financing. Ijara covers leasing.
A law establishing a comprehensive framework for Islamic banking took effect in the summer of 2026. It lets regulators licence dedicated Islamic banks and Islamic banking windows within conventional banks.Authorities expect the sector to attract additional investment. Earlier plans envisaged two full-fledged Islamic banks between 2026 and 2030 and about $1 billion in additional funds.
Open Bank has one shareholder, Future Open Technology Group. The bank operated as Smart Bank before it rebranded in 2025.
Neighbouring Tajikistan adopted its Law on Islamic Banking in 2014. Its first Islamic bank, Tavhidbank, began operating in 2019 after Sohibkorbonk transformed.